Financing Remanufactured Heavy Trucks: Budget and Cash Flow Insights
Intro
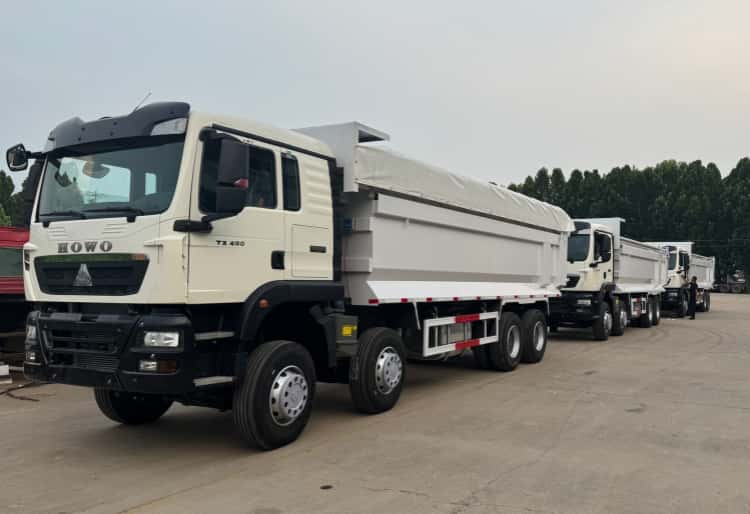
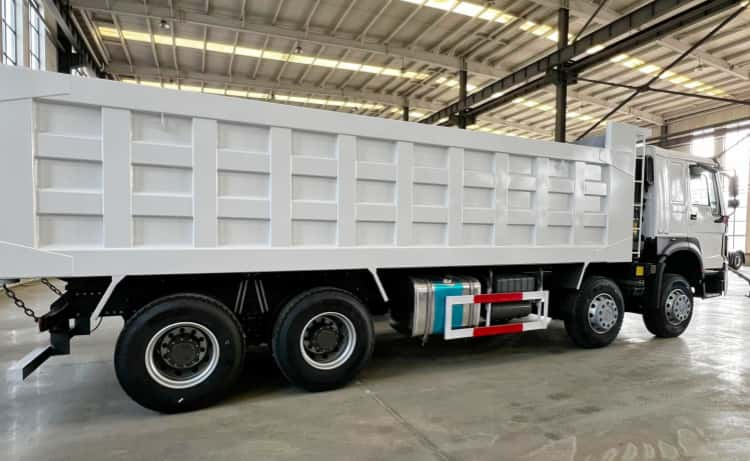
Many fleet owners assume remanufactured heavy trucks for sale are easy to finance just because their purchase price is lower than new trucks. In reality, financiers judge remanufactured heavy trucks based on provable quality, documentation and predictable residual value, not only the upfront invoice number.
Uncertified rebuilds often face financing barriers, while REMAN ROAD certified remanufactured heavy trucks for sale opens up more stable loan structures. Smart financing choices shape your monthly cash flow, not just your initial CAPEX outlay. This section breaks down key financing considerations and practical cash flow insights for fleet planners.
How lenders evaluate remanufactured heavy trucks?
- Lenders separate certified standard reman from informal, self‑declared rebuilds.
- REMAN ROAD’s independent audit and VIN‑locked traceability give lenders clear proof of the reman workflow, component renewal and inspection records.
- Without neutral certification, lenders view the truck as an unknown used asset. They cannot confirm fatigue checks, mandatory part renewal or system testing.
- Collateral value directly impacts approval. Lenders forecast residual value for the end of the loan term.
- Loan tenure is matched to the expected remaining service life of the reman asset.
- The lender will check warranty transferability, because warranty supports long‑term collateral stability.
Down payment differences across asset types
- Brand-new trucks usually have lower down payment ratios, thanks to factory brand recognition and fixed residual benchmarks.
- Ordinary used trucks often require 30% or higher down payment, because lenders price in high failure risk and uncertain resale value.
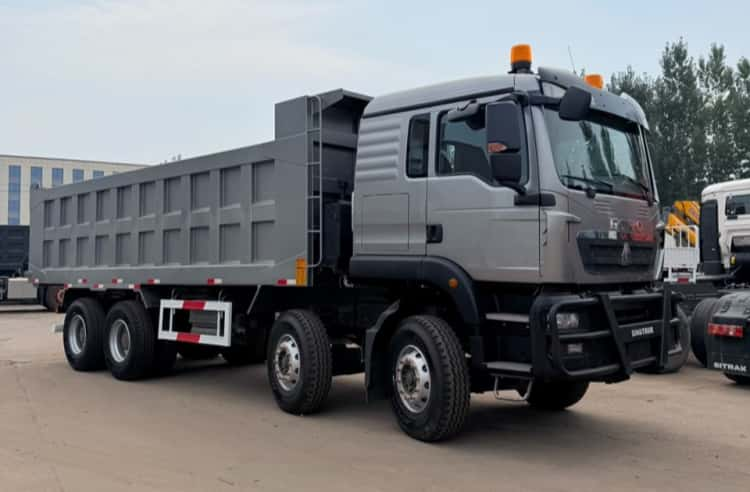
- REMAN ROAD remanufactured heavy trucks sits in the middle. Most lenders accept moderate down payments, better than unvetted used stock, as certification reduces uncertainty.
- A smaller down payment preserves operating cash for fuel, driver payroll and scheduled service.
- Still, you should avoid stretching down payment too thin; higher loan principal increases monthly payment pressure.
Loan structure and repayment options
- Amortising loans are the most common option, with fixed monthly payments over 2–5 years.
- Seasonal repayment plans work well for mining, quarry or seasonal haulage fleets, where revenue fluctuates through the year.
- Balloon payment structures reduce monthly instalments, with a larger final lump sum. This suits fleets that plan to resell or re-remanufacture the truck before the balloon is due.
- Deferred principal payment plans can be arranged for new fleet expansion, but they add interest cost over time.
- Interest rates are tiered. Certified reman qualifies for lower rates than uncertified rebuilds, because the default risk is lower.
Cash flow impacts to model carefully
- Monthly loan instalments are fixed outgoing cash, separate from operating costs and maintenance.
- Even with low monthly payments, you need to reserve cash for scheduled service and mandatory consumable replacements.
- Warranty coverage changes cash flow exposure. If the warranty covers labour and towing, unexpected emergency cash drains are limited.
- Downtime risk is critical for cash flow planning. Cheap uncertified reman may have low loan payments, but sudden breakdowns create unplanned spending and lost revenue.
- Residual value at the end of the loan term is your recovery buffer. Certified remanufactured heavy trucks holds more value, which can cover the balloon payment or serve as a deposit for your next asset.
Common financing pitfalls fleet owners should avoid
- Accepting high-interest financing just to get a low down payment. Over the loan term, interest can erase the original purchase price saving.
- Ignoring fine print that voids financing or warranty if you skip scheduled maintenance.
- Choosing a balloon plan without a clear exit strategy for resale or re-remanufacture.
- Buying uncertified remanufactured heavy trucks with a short loan term, because lenders know its usable lifecycle is unpredictable.
- Forgetting to add insurance, registration and pre‑delivery inspection fees into the financed package. These items add to your total borrowed amount.
Why REMAN ROAD certification improves financing outcomes?
- Independent audit records act as a shared valuation reference for banks, leasing companies and insurance providers.
- Mandatory renewal rules for bearings, seals and wear parts reduce the chance of early asset degradation.
- Transferable warranty means the collateral remains valuable even if you sell the truck mid‑loan.
- Full traceability simplifies asset audits required by finance teams during the loan period.
- Standardised OEM specifications mean spare parts are widely available, which protects the asset’s market liquidity.
Final Takeaway
Financing remanufactured heavy trucks for sale is not only about getting a low monthly payment. The quality proof from REMAN ROAD certification changes how lenders see your collateral, unlocking better rates, reasonable down payment terms and flexible repayment structures.
When you combine suitable loan terms with reliable reman quality, you stabilise monthly cash flow and prevent unexpected financial shocks from early failures or poor residual value. Fleet finance planning should always link loan structure, warranty coverage and residual value forecast together.